
this article is basically a curve of curiosity and it is focused on how asset ownership has been re 2026-10-3 15:26:16 Author: hackernoon.com(查看原文) 阅读量:7 收藏
this article is basically a curve of curiosity and it is focused on how asset ownership has been revolutionized by the Blockchain technology
statistics are derived from the DeFi Llama live analytics dashboard
as at 27th August when the research was done, the RWA market on DeFi Llama looked like this:
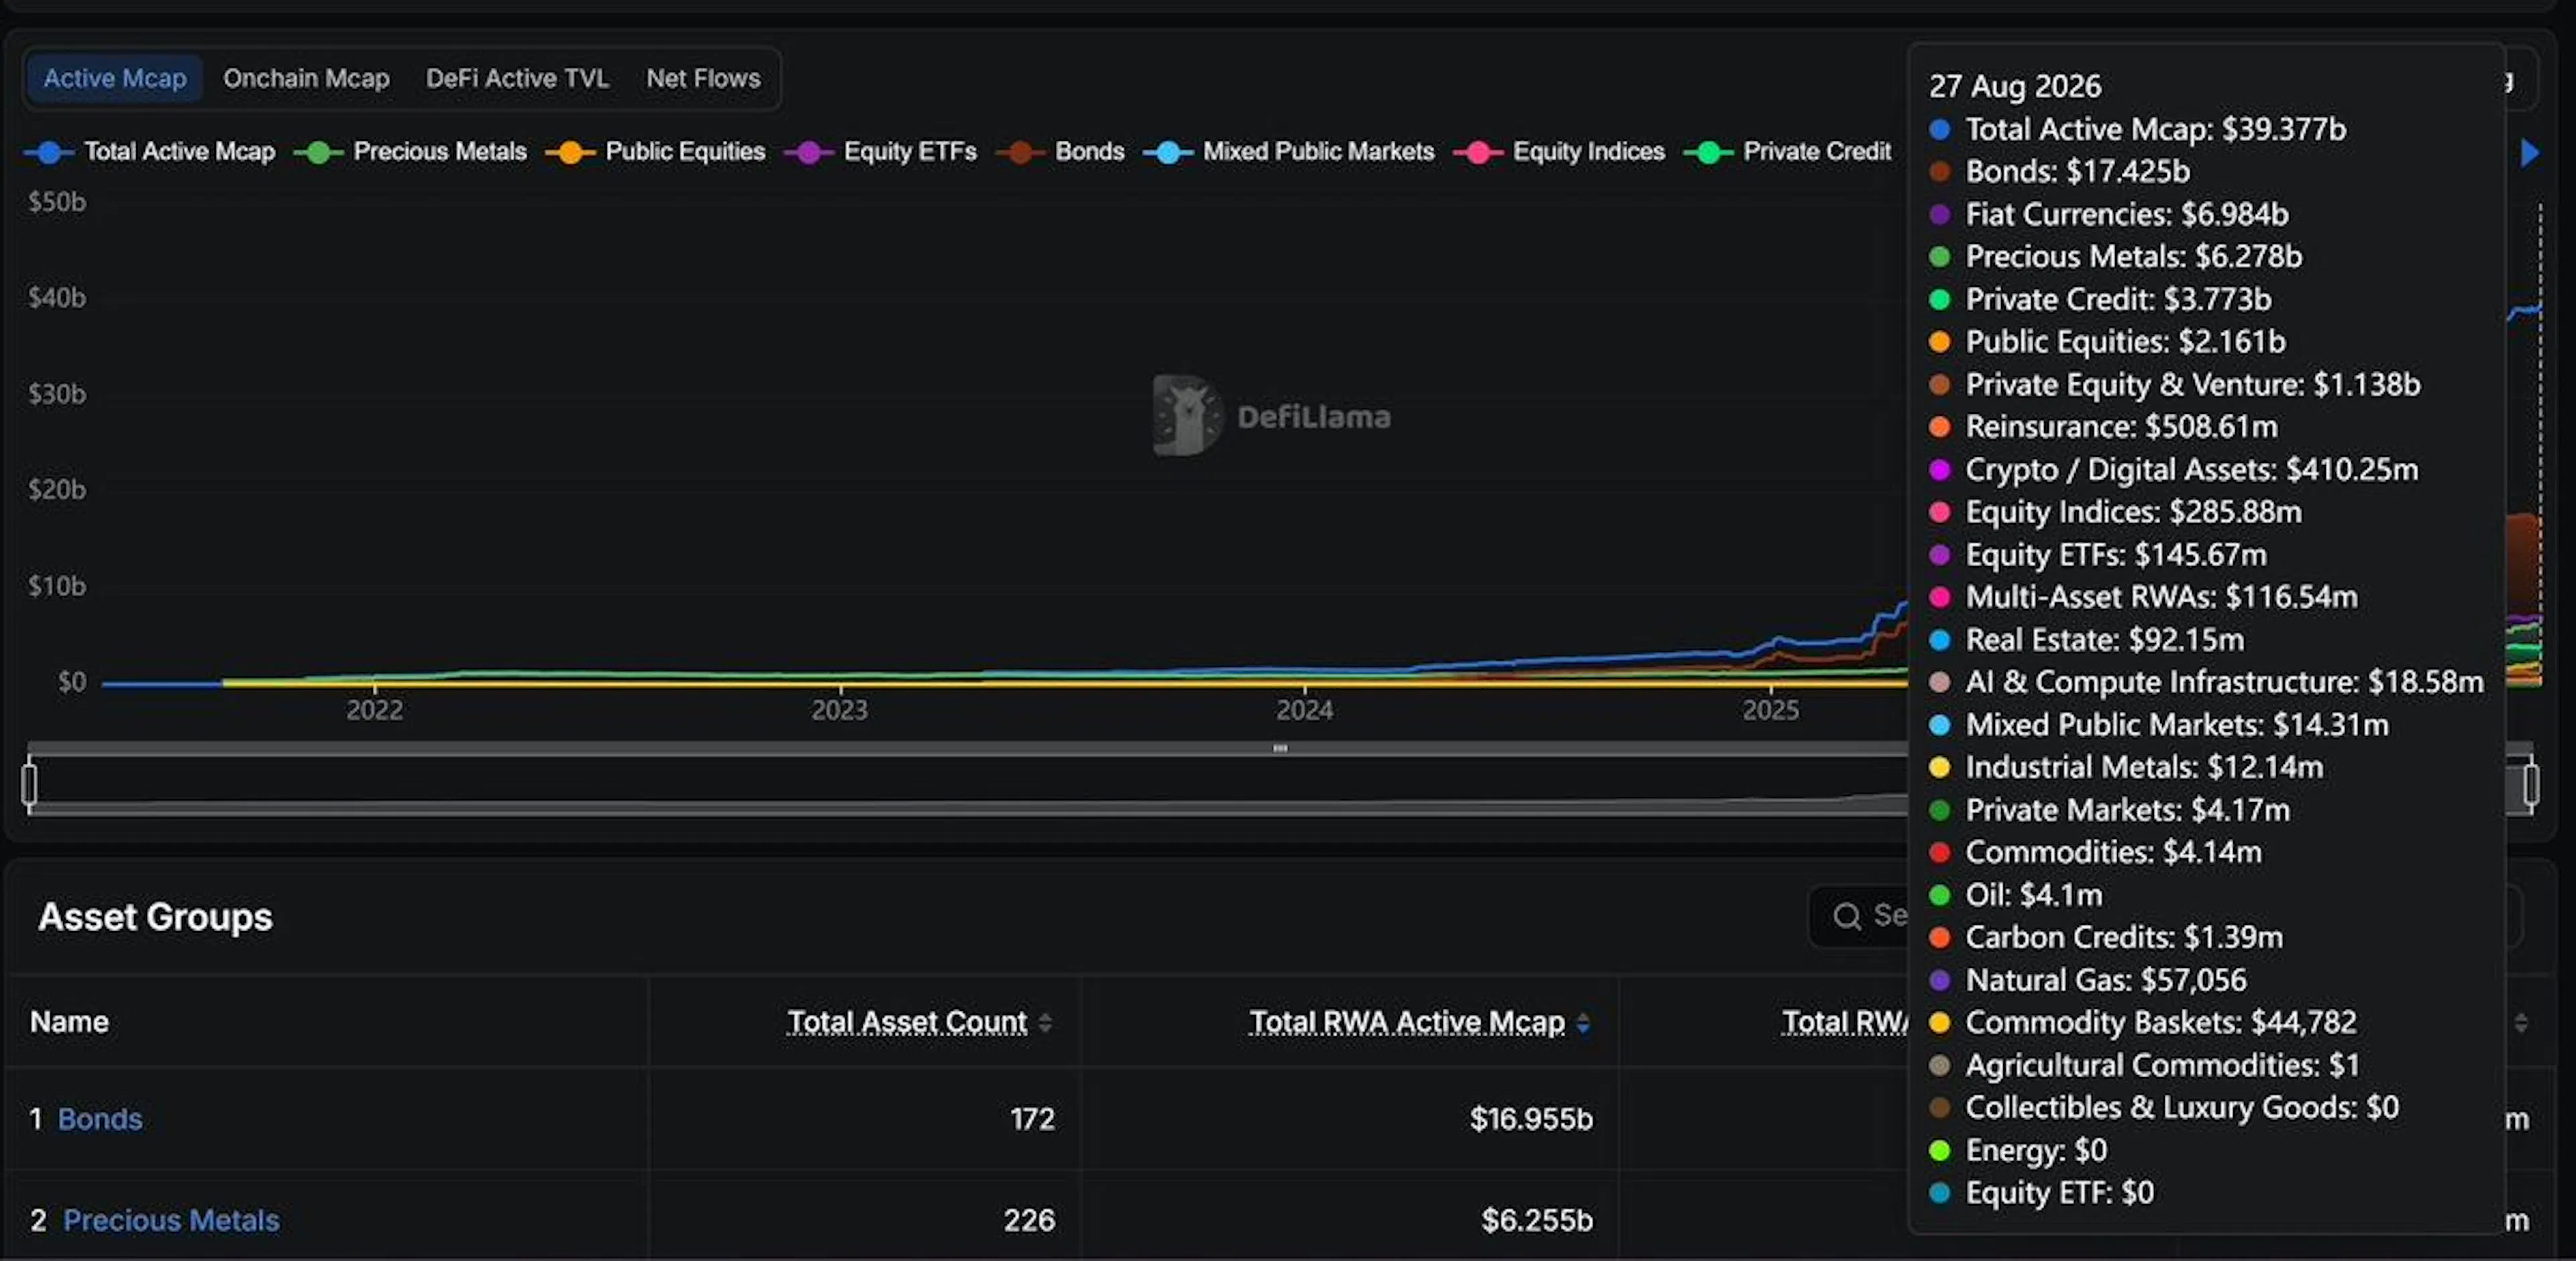 a screenshot of the DeFi Llama RWA dashboard as at 27th August showing the assets and the total active market cap
But before this volume was recorded, it was just a question,
can we take traditional assets onchain?
Now we have over $34B in onchain RWA market capital and about $31B in active Mcap with only a small fraction actually being used in DeFi
The story has changed
We’re far past putting a traditional asset on the blockchain; we’re now concerned with optimizing that asset onchain to become financial infrastructure by figuring out how much of the ownership relationship can be programmed
2021
By 3rd Sept 2021, the Total active Mcap (TaMcap) was $0, 2 days later, a TaMcap of $349.25M was recorded, with precious metals and carbon credits as the assets making up the active Mcap
This test phase was to see if physical commodities like gold and environmental assets could be represented as tokenized claims
Precious metals were easy because they had standardized units and globally recognized value
However, for the carbon credits, it was a different experiment entirely, as they were merely environmental claims that existed traditionally, and they were able to prove that an asset does not need to be moved on-chain for its economic claim to be represented there
Before all this, in April 2021, BENJI token was used to represent a share of the Franklin US Government Money Fund, which was launched on Stellar by Franklin Templeton
He used the Blockchain as a means to record ownership of the fund
An experiment I would describe as the beginning of tokenized ownership
Let’s drift off a little
When you buy a stock in traditional finance, there’s no place your name is written as “owner of the stock”
There are layers of custody. A chain of ownership
Look at Apple Inc., for example:
If you buy a share of Apple through a brokerage account ( a financial account set up with a licensed firm that allows you to buy and sell investments like stocks, bonds, etc.), this is what the ownership trail looks like;
- The transfer agent: people who maintain official records of transactions
- Cede & Co: the legal owner
- DTC: the electronic vault
- Your brokerage firm: a DTC participant
- You (the beneficial owner)
The transfer agent is in charge of issuing the stock from Apple Inc listing Cede & CO as the owner, and DTC holds the legal title to the physical asset in a central vault.
Your broker, e.g. Bamboo claims a chunk of the shares, and then when you purchase a part of it your name is listed as a beneficial owner on the broker’s books
But with the blockchain, it’s a completely different architecture
2022
The RWA market expanded
Over $800M in TaMcap, a +400M on what was recorded in 2021
Private credit onchain became a thing
Several protocols like Maple and Goldfinch tried bringing credit markets onchain, while Centrifuge walked the path of loans
Trying to bring credit markets onchain was a different thing entirely
With tokenized Gold, a claim associated with a physical commodity is being represented but tokenized credit is basically representing a claim based on someone’s ability to repay in the future
Now there’s risk, legal agreements, underwriting
Bringing credit markets onchain was never going to eliminate these underlying relationships and protocols like Terra/Luna and Three Arrows Capital showed exactly that
It was made clear that even though credit markets were now made transparent and transferable, the risk will always be there
2023
Crypto native yields were taking a dive, then tokenized treasuries brought very attractive yields for users
Tokenized US Treasury products had a 752% increase from January to the end of the year
Assets onchain became very attractive economically
What was more important in this stage of evolution was infrastructure, and several products came in with several approaches
- Matrixdock’s STBT employed a rebasing structure in which an increase in profit brought about an increase in the number of tokens held
- Backed’s blB01 used a non-rebasing structure where the price appreciates instead of the token held increasing
These tokens became more than on-chain representation; they were financial infrastructure
The non-rebasing token was deemed ideal as collateral
2024
Institutions began to validate infrastructures
Frank Templeton introduced P2P transfers of BENJI between eligible shareholders
Transferability entered the game
BlackRock’s BUIDL launched with Securitize, showing the possibility that traditional finance institutions can use Blockchain infrastructures to distribute, settle, and manage their products
the RWA market reached $3B by the end of 2024
With tokenized gold products, representation, transferability, self-custody, redeemability, and composability were achieved
2025
The tokenized market became so broad, with products like Bonds, precious metals, private credit, crypto digital assets, and private equity spearheading the market
with the TaMcap surpassing $16B, more than five times what it was in 2024
tokenized assets became more than what you’d simply hold
It became;
- Collateral
- Liquidity
- Capital for yield
and so much more……
This growth in the tokenized market has, however, revealed the limitations of tokenization
with real estate, it was seen that a token can function while the real-world asset experiences operational problems
Token trading did not guarantee a properly maintained building; a landlord could still fail to keep his building habitable
His competence is not guaranteed, as property management cannot be tokenized
2026
A different problem has emerged
The market is over $39B now
Studying the DeFi Llama RWA dashboard taught me something
A token being onchain doesn’t make it DeFi native
there’s recorded roughly $4B in DeFi active TVL against over $39B in onchain RWA
The integration of these assets in the crypto financial system still has a long way to go as they still remain largely isolated from DeFi
RWA ownership is a stack; it’s not “you own it or don’t”
The stack includes:
- Representation
- Economic exposure
- Transferability
- Self custody
- Redeemability
- Legal ownership
- Programmable ownership
The relationship different products have with this stack depends on what they’re trying to offer
More markets are coming onchain ➔ ownership relationship is not necessarily fully decentralized ➔ DeFi integration is so behind the tokenized value of the market
The RWA paradox
Tokenization ≠ Ownership ≠ Composability
The biggest change the RWA market would see with time is having about 80% of products that are onchain fully integrated in DeFi
at this stage there are still question marks about where tokenization is right now despite the progress that has occurred in the past 5 years
would tokenization ever be fully decentralized?
can the underlying intermediaries be done away with?
Can code eventually take the place of legal agreements?
Maybe these assets will never be paired without these intermediaries; maybe they will,
But whatever it is, the future of tokenization is an interesting one.
如有侵权请联系:admin#unsafe.sh